

Signed in as:
filler@godaddy.com
Receiving a notice from the IRS can be unsettling, particularly when the letter mentions additional taxes, liens, levies, bank accounts, wages, or other collection action. The most important thing to understand is that not every IRS notice means the same thing, and the rights and deadlines associated with each notice can be very different.
Ignoring an IRS notice rarely makes the problem disappear. Depending on the notice, failing to respond can result in additional tax being assessed, penalties and interest continuing to accrue, a federal tax lien being filed, or the IRS moving closer to enforced collection.
Below is an explanation of several common IRS notices, what they mean, what you should do, important response deadlines, and mistakes to avoid.
Being in the Real Estate business can be one of the most tax advantaged professions. Learn about the complex tax laws that can save you thousands each year.
Many service professionals miss tax deductions every year. Let us review your tax returns to find deductions you may have overlooked.
We specialize in helping small and large Transportation companies reduce taxes. Learn about the most commonly missed tax deductions available only to transportation workers.
You work hard to earn every dollar. Learn of the many commonly missed deductions properly file taxes as a gig worker and of the many commonly missed deductions.
Most tax preparers don't know the Special Rules for Notaries. Don't allow yourself to be over taxed this year.
Have you opened a new location, redesigned your shop, or added a new product or service? These business investments can save on taxes.
Learn more about tax savings strategies that you may be able to take on your next tax return.
An IRS CP2000 notice is generally issued when information reported to the IRS by a third party does not match information reported on your federal income tax return.
Employers, banks, brokerage firms, payment processors, retirement plans, and other organizations report income and payment information to the IRS on forms such as:
When the IRS computer-matching system identifies a discrepancy, it may issue a CP2000 proposing changes to your return.
A CP2000 is a proposed adjustment. It is not itself a tax bill and is not the same thing as a traditional IRS audit.
The IRS generally instructs taxpayers to respond within 30 days from the date of the notice, or generally 60 days if the taxpayer lives outside the United States. Your actual CP2000 contains the response deadline that applies to your case.
First, compare the CP2000 carefully with the tax return you filed and the income documents identified by the IRS.
Determine whether:
If you agree, follow the instructions provided with the notice.
If you disagree, provide a clear explanation and supporting documentation showing why the proposed adjustment is incorrect.
The IRS may accept your explanation, request additional documentation, or issue a revised proposed adjustment.
If the matter is not resolved during the CP2000 process, the IRS may eventually issue a statutory Notice of Deficiency, which can provide the right to petition the United States Tax Court.
That later deadline is extremely important and should not be confused with the initial CP2000 response period.
A CP2000 is a proposal, not necessarily the final word. Review the underlying tax return and information documents before agreeing to additional tax.

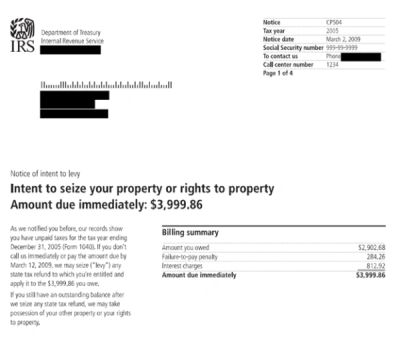
An LT11 is one of the most serious IRS collection notices.
It generally means the IRS has previously attempted to collect an unpaid tax liability and is now notifying you that it intends to levy property or rights to property if the matter is not resolved.
The notice also provides important Collection Due Process, or CDP, hearing rights.
A levy may potentially affect assets such as:
An LT11 generally provides 30 days to request a Collection Due Process hearing.
The deadline shown on your particular notice controls.
Do not treat an LT11 as another ordinary collection reminder.
Immediately:
A CDP hearing may allow the taxpayer to present collection alternatives such as an installment agreement, Offer in Compromise, or other appropriate collection resolution.
In certain circumstances, a taxpayer may also challenge the underlying liability if there was no prior opportunity to dispute it.
If a timely CDP request is filed, the case may be reviewed by the IRS Independent Office of Appeals before the proposed levy proceeds, subject to applicable exceptions.
A timely CDP request can also preserve important judicial review rights.
LT11 is a major escalation point. The taxpayer may have valuable appeal rights that can expire if the notice is ignored.
Letter 1058 serves a function similar to LT11. It advises the taxpayer that the IRS intends to levy property or rights to property and provides Collection Due Process rights.
Letter 1058 is commonly associated with cases being handled through IRS Collection and may be issued in connection with a Revenue Officer case.
The taxpayer generally has 30 days to request a Collection Due Process hearing.
Always use the exact deadline printed on the letter.
Immediately determine:
If no appropriate response is made, the IRS may proceed toward levy action after applicable requirements have been satisfied.
If a timely CDP hearing is requested, the taxpayer may be able to present appropriate collection alternatives to IRS Appeals.
A Letter 1058 should be addressed immediately, particularly because appeal rights may be time-sensitive.
What Is an IRS CP2000 Notice?
An IRS CP2000 notice is generally issued when information reported to the IRS by a third party does not match information reported on your federal income tax return.
Employers, banks, brokerage firms, payment processors, retirement plans, and other organizations report income and payment information to the IRS on forms such as:
When the IRS computer-matching system identifies a discrepancy, it may issue a CP2000 proposing changes to your return.
A CP2000 is a proposed adjustment. It is not itself a tax bill and is not the same thing as a traditional IRS audit.
The IRS generally instructs taxpayers to respond within 30 days from the date of the notice, or generally 60 days if the taxpayer lives outside the United States. Your actual CP2000 contains the response deadline that applies to your case.
First, compare the CP2000 carefully with the tax return you filed and the income documents identified by the IRS.
Determine whether:
If you agree, follow the instructions provided with the notice.
If you disagree, provide a clear explanation and supporting documentation showing why the proposed adjustment is incorrect.
The IRS may accept your explanation, request additional documentation, or issue a revised proposed adjustment.
If the matter is not resolved during the CP2000 process, the IRS may eventually issue a statutory Notice of Deficiency, which can provide the right to petition the United States Tax Court.
That later deadline is extremely important and should not be confused with the initial CP2000 response period.
A CP2000 is a proposal, not necessarily the final word. Review the underlying tax return and information documents before agreeing to additional tax.
What Is an IRS CP2000 Notice?
An IRS CP2000 notice is generally issued when information reported to the IRS by a third party does not match information reported on your federal income tax return.
Employers, banks, brokerage firms, payment processors, retirement plans, and other organizations report income and payment information to the IRS on forms such as:
When the IRS computer-matching system identifies a discrepancy, it may issue a CP2000 proposing changes to your return.
A CP2000 is a proposed adjustment. It is not itself a tax bill and is not the same thing as a traditional IRS audit.
The IRS generally instructs taxpayers to respond within 30 days from the date of the notice, or generally 60 days if the taxpayer lives outside the United States. Your actual CP2000 contains the response deadline that applies to your case.
First, compare the CP2000 carefully with the tax return you filed and the income documents identified by the IRS.
Determine whether:
If you agree, follow the instructions provided with the notice.
If you disagree, provide a clear explanation and supporting documentation showing why the proposed adjustment is incorrect.
The IRS may accept your explanation, request additional documentation, or issue a revised proposed adjustment.
If the matter is not resolved during the CP2000 process, the IRS may eventually issue a statutory Notice of Deficiency, which can provide the right to petition the United States Tax Court.
That later deadline is extremely important and should not be confused with the initial CP2000 response period.
A CP2000 is a proposal, not necessarily the final word. Review the underlying tax return and information documents before agreeing to additional tax.